
Home Loan EMI in Hyderabad (2026): Rates, EMI Table and How to Pay Less Interest
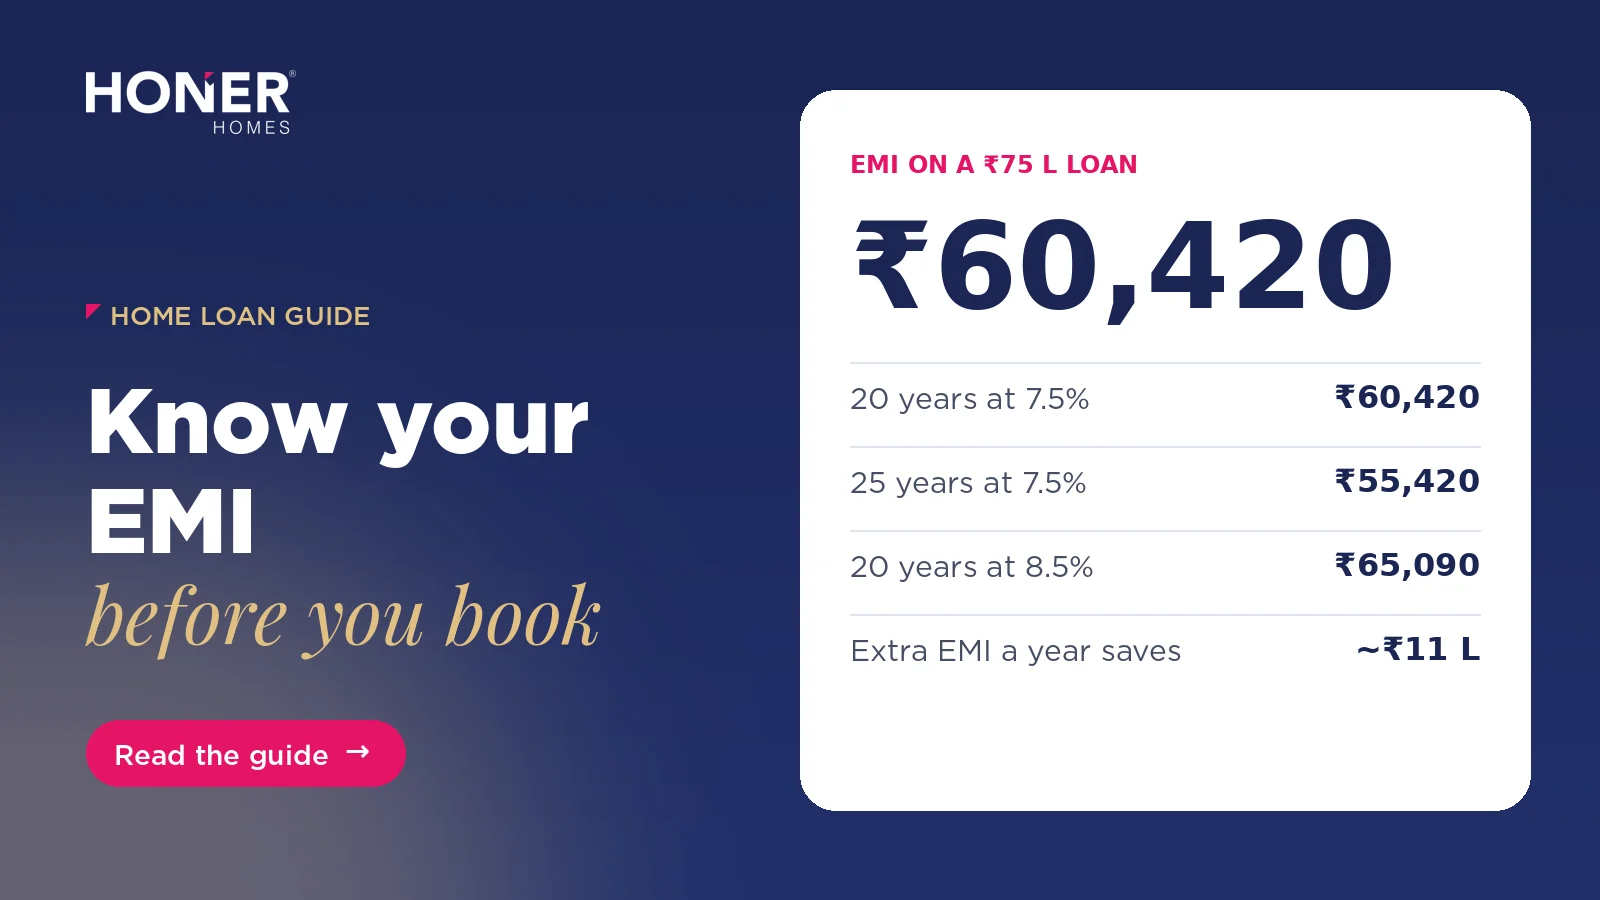
Quick answer: In November 2026, home loan rates from the big lenders start at about 7.15% to 7.70% a year for borrowers with good credit scores. The RBI raised the repo rate by 0.25% to 5.50% on 7 October 2026, so floating-rate EMIs are edging up.
On a ₹75 lakh loan for 20 years at 7.5%, the EMI is about ₹60,400 a month, and you pay about ₹70 lakh in interest over the full term.
Why read this, and how it helps you
The EMI decides which flat you can actually afford, not the brochure price. This guide shows today's rates, what you will pay each month, and simple steps that can save you lakhs over the life of the loan.
Home loan rates in November 2026
- LIC Housing Finance: Starting rate (p.a.): 7.15%
- SBI: Starting rate (p.a.): 7.25%
- HDFC Bank: Starting rate (p.a.): 7.45%
- Axis Bank: Starting rate (p.a.): 7.55%
- ICICI Bank: Starting rate (p.a.): 7.70%
Starting rates as listed on 11 November 2026 for salaried borrowers with high credit scores. Your rate depends on your credit score, income, loan amount and the lender's offer that week. Always confirm with the lender.
Most home loans in India are floating rate and linked to an external benchmark, usually the RBI repo rate. When the repo rate moves, your rate moves with it, usually within one quarter.
EMI table: what you will pay each month
- ₹50 lakh: 20 years at 7.5%: ₹40,280; 25 years at 7.5%: ₹36,950; 20 years at 8.5%: ₹43,390
- ₹75 lakh: 20 years at 7.5%: ₹60,420; 25 years at 7.5%: ₹55,420; 20 years at 8.5%: ₹65,090
- ₹1 crore: 20 years at 7.5%: ₹80,560; 25 years at 7.5%: ₹73,900; 20 years at 8.5%: ₹86,780
A quick rule: at 7.5% for 20 years, every ₹1 lakh you borrow costs about ₹806 a month.
How the October 2026 repo hike affects you
A 0.25% rise on a ₹75 lakh, 20-year loan adds about ₹1,150 to the monthly EMI. Many banks keep the EMI the same and stretch the tenure instead, which quietly adds interest. If your bank does this, ask it to raise the EMI instead, or make a small prepayment each year to keep the tenure in check.
Five ways to pay less interest
- Raise your credit score above 750 before you apply. The best rates in the table go only to high scores. Clear card dues and avoid new loans for six months.
- Pay one extra EMI a year. On a ₹75 lakh, 20-year loan at 7.5%, one extra EMI each year closes the loan in about 17 years and saves roughly ₹11 lakh in interest.
- Choose the shortest tenure you can manage. The 25-year EMI is lower, but you pay about ₹21 lakh more interest on a ₹75 lakh loan.
- Ask for a rate review every year. If new customers get a lower rate, your bank can usually reset yours for a small fee. Switching banks is the fallback.
- Add a co-applicant. A working spouse adds income for eligibility and both of you can claim the tax benefits.
How much loan can you get?
Banks usually keep all your EMIs within 40% to 50% of your take-home pay. On a take-home of ₹1.5 lakh a month, that means total EMIs of about ₹60,000 to ₹75,000, which supports a loan of roughly ₹75 to ₹90 lakh at today's rates.
The RBI also caps how much of the property price a bank can lend, so you need a down payment. Read our down payment guide for the exact limits.
Tax benefits in brief
Under the old tax regime, you can claim up to ₹1.5 lakh of principal under Section 80C and up to ₹2 lakh of interest under Section 24(b) for a self-occupied home. Under the new regime, these deductions do not apply to a self-occupied home. Tax rules change; check with your CA. Not tax advice.
Before you sign the loan
- Get a sanction letter before you book the flat, so you know your real budget.
- Check that the project is approved by your lender. Most banks pre-approve RERA-registered projects, which speeds up disbursement.
- For an under-construction flat, the bank pays in stages as construction progresses. You pay only interest (pre-EMI) on the amount released until possession, unless you choose full EMI from the start.
Next, see the full step-by-step buying checklist and what stamp duty and registration add on top.
Frequently asked questions
What is the EMI for a ₹50 lakh home loan in Hyderabad? At 7.5% for 20 years, the EMI is about ₹40,280 a month. At 25 years it falls to about ₹36,950, but you pay about ₹14 lakh more interest.
What is the current repo rate in India? The RBI raised the repo rate by 0.25% to 5.50% on 7 October 2026. Check the RBI website for any later change.
Is a fixed or floating home loan better? Most buyers choose floating rates because they are lower at the start and you can prepay without penalty. Fixed rates are higher and often reset after a few years anyway.
Can I prepay my home loan without a penalty? Yes. Banks cannot charge a prepayment penalty on floating-rate home loans taken by individuals.
Does the home loan cover stamp duty and registration? Usually not. Plan to pay stamp duty, registration and other charges from your own savings.
