
Home Loan Eligibility in 2026: How Much Loan Can You Get on Your Salary?
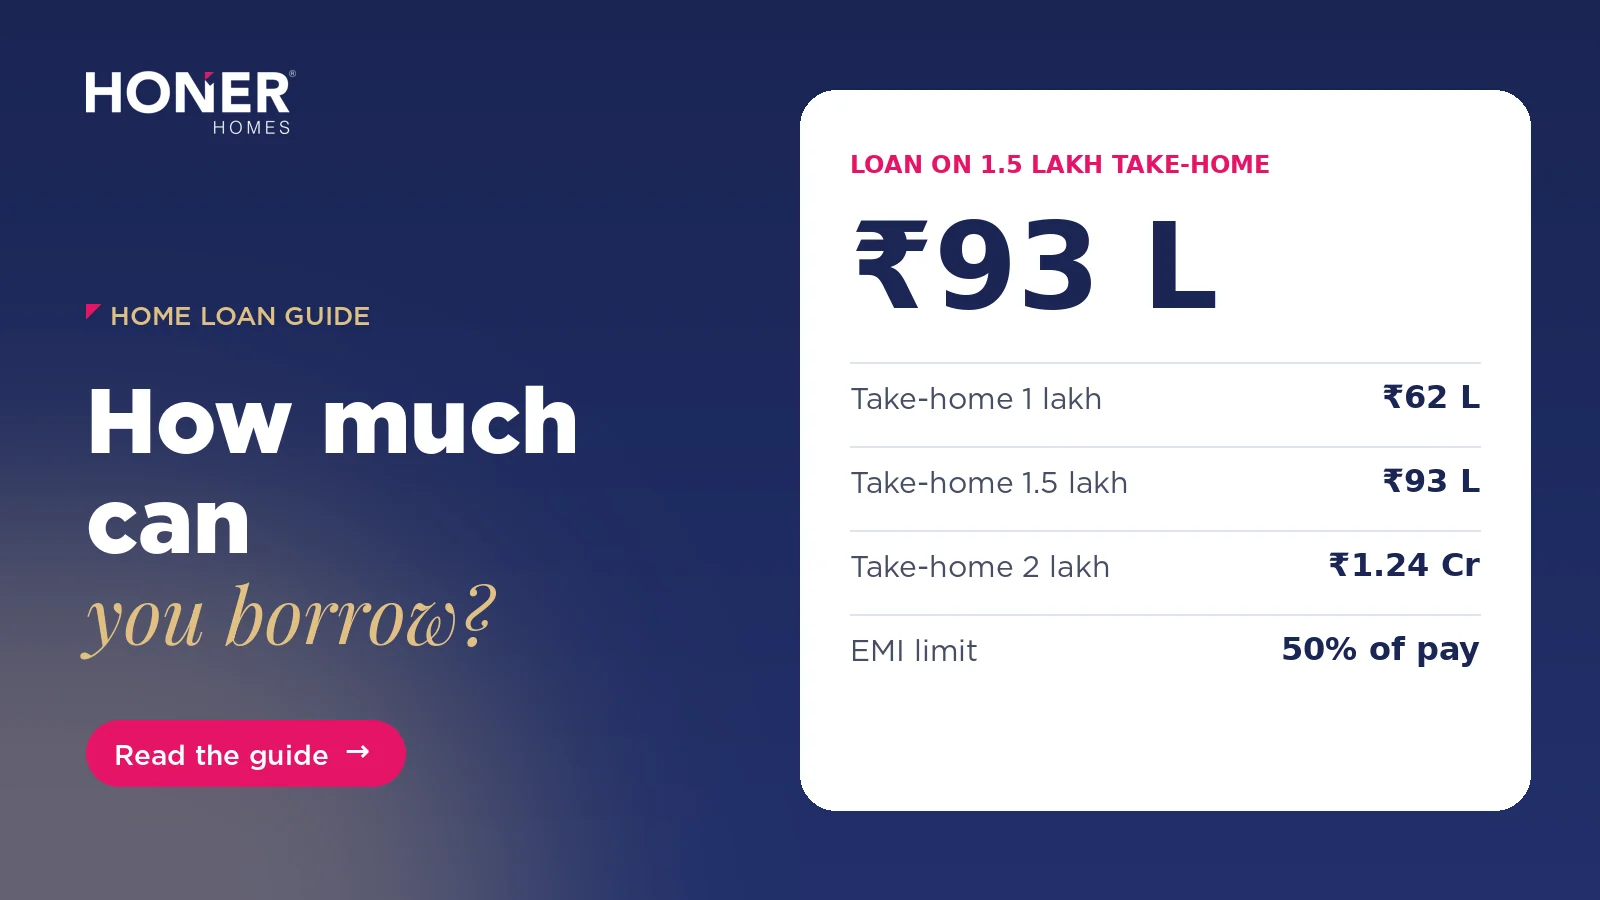
Quick answer: Most banks let your total EMIs reach 40% to 50% of your monthly take-home pay. At today's rates (about 7.5% for 20 years), that works out to roughly:
- ₹1 lakh take-home: a loan of about ₹50 to ₹62 lakh
- ₹1.5 lakh take-home: about ₹75 to ₹93 lakh
- ₹2 lakh take-home: about ₹1 crore to ₹1.24 crore
Existing EMIs, your age and your credit score can push this up or down.
Why read this, and how it helps you
Knowing your loan limit before you visit projects stops you from falling for a flat you can't finance. This guide explains how banks calculate it and how to raise it.
The five things banks check
- Take-home income: salary after tax and deductions, or average business income from your tax returns.
- Existing EMIs: car loans, personal loans and credit card dues reduce what is left for the home loan.
- Age: banks usually want the loan repaid by about 60 to 65, so older applicants get shorter tenures and smaller loans.
- Credit score: 750 and above gets the best rates and the most flexibility.
- The property: the bank lends only up to 75% to 90% of its value under RBI rules, and only for approved projects.
Salary to loan: a quick table
- ₹1 lakh: EMI at 40%: ₹40,000; EMI at 50%: ₹50,000; Loan at 7.5%, 20 years: ₹50 to ₹62 lakh
- ₹1.5 lakh: EMI at 40%: ₹60,000; EMI at 50%: ₹75,000; Loan at 7.5%, 20 years: ₹75 to ₹93 lakh
- ₹2 lakh: EMI at 40%: ₹80,000; EMI at 50%: ₹1 lakh; Loan at 7.5%, 20 years: ₹99 lakh to ₹1.24 crore
Assumes no other loans. Use our EMI calculator to test other amounts and tenures.
How existing loans cut your limit
Say you take home ₹1.5 lakh and pay a ₹15,000 car EMI. At a 50% limit, the bank allows ₹75,000 of total EMIs, so only ₹60,000 is left for the home loan. That one car loan cuts your home loan by about ₹18 lakh.
Six ways to get a bigger loan
- Add a co-applicant. A working spouse or parent adds their income. Co-owners can also share the tax benefits.
- Close small loans first. Clearing a personal loan or card balance frees up eligibility quickly.
- Choose a longer tenure. A 25 or 30-year tenure lowers the EMI per lakh, though you pay more interest.
- Show all your income. Include regular bonuses, rental income and variable pay where the bank accepts it.
- Fix your credit report. Check for errors and settle any overdue accounts months before you apply.
- Pick a bank-approved project. Approved projects are processed faster, and banks are more comfortable lending at the top of their range.
Your loan is not the whole budget
The bank will not fund the down payment, stamp duty, registration or GST. Read our down payment guide and use the stamp duty calculator to see the full amount you need.
Frequently asked questions
How much home loan can I get on a ₹1 lakh salary? If you take home ₹1 lakh a month and have no other loans, most banks will lend about ₹50 to ₹62 lakh over 20 years at around 7.5%.
What is FOIR in a home loan? FOIR (fixed obligation to income ratio) is the share of your income that goes to all EMIs. Banks usually cap it at 40% to 50%.
Does a co-applicant increase home loan eligibility? Yes. The co-applicant's income is added to yours, which raises the loan amount you can get.
What credit score do I need for a home loan? Most lenders want 700 or above, and 750 or above gets the best rates.
